Taiwan Stock Loans (股票質押) on TWSE-Listed Shares
In Taiwan, a stock loan lets a shareholder borrow against TWSE-listed shares without selling them. The shares are pledged as collateral: ownership and voting rights stay with the holder, and the full position is returned on repayment. Loans typically run 12 to 36 months, in TWD or another major currency.
Local terms: 股票質押
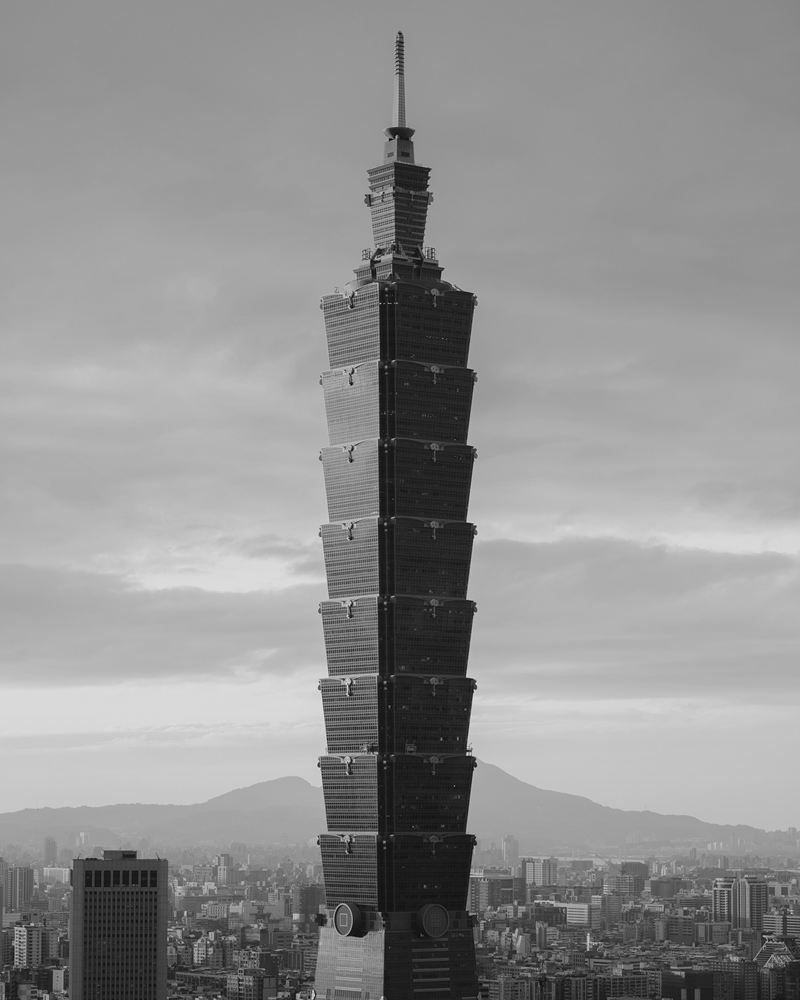
How do Taiwan stock loans work?
The firm arranges stock loans against shares listed on one principal cash equity venue in Taiwan: TWSE. Founders, family offices, controlling shareholders and other substantial holders use them to release cash from a listed position without selling it.
The borrower keeps beneficial ownership throughout, and voting control and the share register are not disturbed. The full position is returned on repayment. Terms are calibrated to the specific position, and indicative terms typically follow within one to two business days of an enquiry.
Key facts for Taiwan stock loans:
| Exchange | Taiwan Stock Exchange (TWSE) |
|---|---|
| Regulator | Financial Supervisory Commission (FSC) |
| Trading currency | TWD |
| Settlement and depository | T+2; depository: Taiwan Depository & Clearing Corporation (TDCC) |
| Indicative LTV range | Discussed per position (no published rate card or band) |
| Typical tenor | 12 to 36 months |
| Recourse options | Non-recourse, limited-recourse or full-recourse |
| Disclosure thresholds relevant to a pledge | More than 5% (lowered from 10% on 10 May 2024), then each 1% change (Securities and Exchange Act, Article 43-1). Who must disclose a pledge, and when |
| Foreign-ownership limits | Discussed per position |
| Local terms | 股票質押 |
Regulatory references for a specific transaction are mapped at the structuring stage with the borrower’s chosen counsel. This summary is for general orientation and is not legal advice.
Taiwan Stock Exchange (TWSE): listing, indices and liquidity.
Taiwan Stock Exchange is the principal cash equity venue in Taiwan. It was established in 1962 and is overseen today by the Financial Supervisory Commission (FSC).
Its principal indices are TAIEX, FTSE TWSE Taiwan 50. Listing standards and continuing obligations are set out in the TWSE Operating Rules and the Securities and Exchange Act.
The principal Taiwanese equity venue, with deep concentration in semiconductor and electronics issuers (TSMC alone constitutes a substantial share of TAIEX market capitalisation). Foreign institutional inflows shape day-to-day liquidity profiles.
Segments: TWSE Main Board; Taipei Exchange (TPEx, formerly GreTai) - OTC market. Each segment has its own listing standards and continuing obligations, and these feed into the eligibility review for an institutional position.
How do liquidity and the index affect a loan?
The Taiwan Stock Exchange main board sits alongside the Taipei Exchange (TPEx) OTC market, benchmarked by the broad TAIEX and the large-cap FTSE TWSE Taiwan 50. The defining characteristic is concentration: semiconductor and electronics issuers dominate the index, and a single foundry constitutes a substantial share of TAIEX market capitalisation.
That gives the largest names exceptional depth for pledge sizing, but it also means a portfolio of Taiwan large-caps can be heavily correlated to one sector. The firm weighs that concentration when calibrating an advance and any margining, since a single-sector shock would move much of the collateral together.
How is a loan against TWSE shares structured?
Custody and settlement follow Taiwanese conventions through the local depository, with foreign holders operating under the qualified-investor registration framework that is verified before a pledge is taken. The structural theme is sector concentration: because semiconductor and electronics names dominate, the firm assesses how correlated the collateral is to that single sector and sizes accordingly.
Article 43-1 sets the public threshold at more than 5%, lowered from 10% on 10 May 2024, with a report at each 1% change. Director and insider holdings carry separate constraints that bear on timing. Where the position sits on the TPEx OTC market rather than the main board, thinner liquidity narrows what can be advanced.
Funding is set in TWD or cross-currency once custody is confirmed.
Which TWSE-listed shares qualify for a stock loan?
TWSE is among the deepest cash equity pools in the world. Eligibility for an institutional position there turns mainly on single-stock factors: free float, average daily trading volume, shareholder concentration and the holder’s regulatory profile. Market-level liquidity is rarely the constraint.
For a specific position, the review looks at free float and average daily trading volume against the size of the pledge. It considers the shareholder’s status (controlling shareholder, substantial shareholder, director or otherwise) and the disclosure that follows from it.
It also covers the issuer’s sector and listing segment, and any concurrent rules such as takeover-code mechanics, foreign-ownership caps or regulated-industry limits. Finally, it sets the structure sought: loan-to-value, tenor, currency, recourse profile and custody.
How much can you borrow against TWSE-listed shares?
The amount is the loan-to-value, set against the liquidity and free float of the specific shares. No rate sheet or band is published. Indicative terms are issued after a review of the position, and a non-recourse structure runs at a lower ratio than full recourse on the same shares.
Which disclosure rules apply to a pledge of TWSE-listed shares?
The principal regulatory reference on TWSE is Securities and Exchange Act Art. 43-1. Reporting levels, step thresholds and their interpretation for a given transaction follow the underlying rules and any national-law overlays.
These are mapped at the structuring stage, with the borrower’s chosen counsel. For controlling shareholders, directors and other regulated holders, further regimes apply: takeover rules, insider-dealing rules under the FSC framework, and limits on dealing in defined windows. Depending on the market, those windows come from listing rules, market-abuse rules or company policy.
The disclosure footprint of each transaction is mapped at the structuring stage, and sequencing, wording and any concurrent regulatory communications are managed to match.
How does disclosure work in practice in Taiwan?
Taiwan’s substantial-ownership trigger was lowered from 10% to 5% on 10 May 2024. Under Article 43-1 of the Securities and Exchange Act, a holder must now report once the interest exceeds 5%, with a further report at each 1% change. Directors and insiders also face their own dealing-window and reporting constraints, so a controlling holder is seldom fully private.
Foreign positions run through the qualified-investor framework, and inbound institutional flows are a defining feature of the market. The borrower’s regulatory status and the issuer’s sector are therefore weighed closely when the pledge is structured and its disclosure footprint mapped.
These references are public regulatory citations, published for information only and not legal advice. The primary sources should be consulted directly: the TWSE Operating Rules, the Securities and Exchange Act and the applicable statutory instruments.
Each enquirer should take independent legal advice in the relevant jurisdiction for any specific transaction.
How do you get a stock loan against TWSE-listed shares?
The engagement runs in five stages, from confidential enquiry to funding, with senior principals throughout. It works the same way in every market.
For a position on TWSE, the structuring stage covers settlement under local conventions and custody with a qualified local custodian. It also covers a TWD or cross-currency loan, and the timing of any disclosure under the FSC regime.
What might a stock loan in Taiwan look like? An illustrative example
For illustration only, take a holder of TWD 3 billion in a large-cap TAIEX company. The pledge releases cash while the shares remain registered to the holder and the upside is kept. The loan-to-value sets how much is released.
No percentage or band is published for it, because the ratio is a property of the collateral rather than of the product. The ratio reflects the traded volume, free float and price volatility of that line, and how correlated the line is to the semiconductor and electronics complex that dominates the index.
It also reflects how large the pledge is against both the issuer and the holder’s wider wealth, and the Taiwanese settlement and enforcement regime. Finally, it reflects the funding currency and any qualified-investor or Article 43-1 disclosure constraint. It is fixed only after the actual holding has been reviewed.
The loan can be drawn in TWD or on a cross-currency basis against the Taiwan-dollar collateral. The holding size is round and entirely hypothetical, included only to show how an advance is sized against a Taipei-listed position.
Illustrative only: not an offer, a quotation, or a commitment to lend.
Taiwan stock loans: frequently asked questions.
Q · 01
What is the typical loan-to-value for a stock loan against TWSE-listed positions?
There is no typical figure: loan-to-value on TWSE is calibrated to the specific position, and no rate sheet or band is published.
The main drivers are free float, average daily trading volume, volatility and the borrower’s regulatory profile. A large, liquid TWSE name supports a higher ratio than a thinly traded or recently listed one, and non-recourse runs lower than full recourse on the same shares.
Q · 02
Which TWSE-listed segments are eligible for stock loans?
Positions in any Taiwan Stock Exchange segment can be considered, with eligibility assessed case by case.
The segments are: TWSE Main Board; Taipei Exchange (TPEx, formerly GreTai) - OTC market. Higher-tier segments (premium, large-cap or main market) are usually more straightforward to structure than growth or SME segments, mainly because of free float and liquidity.
Q · 03
In which currency can a TWSE stock loan be denominated?
The default is TWD, the listing currency, and cross-currency loans are common.
For example, a TWD-denominated TWSE position can be financed with a USD or EUR loan. The cross-currency element brings hedging, settlement and tax considerations, which the documentation addresses.
Q · 04
Are there foreign-ownership constraints on TWSE-listed shares relevant to a pledge?
Sometimes: foreign-ownership rules vary by issuer and by sector on TWSE.
Regulated sectors (banking, telecoms, defence, natural resources and others) commonly carry ownership caps and notification requirements that interact with a collateralised structure. The structuring review addresses these expressly for each position.
Further reading on Taiwan stock loans.
Securities-Based Lending: How Securities-Backed Loans Work
The main guide: the pledge, the loan-to-value, tenor, recourse and custody.
Read →Share Pledge Disclosure Rules by Market
Share pledge disclosure rules by market: who must disclose, the threshold and the deadline. In Taiwan, a company reports an insider’s pledge within five days.
Read →Cross-Currency Stock Loans
Cross-currency stock loans: financing a GBP-listed position with a USD loan, or an HKD position in EUR. How the currency choice, hedging and settlement work.
Read →Which other Asia-Pacific markets are covered?
Hong Kong · Japan · China · South Korea · Singapore · Australia · New Zealand · India · Thailand · Indonesia · Malaysia · Philippines · Vietnam

A specific Taiwan position to discuss?
Submit a confidential enquiry. A senior principal will respond within one business day.